Dimensional Fund Advisors Vice President, Apollo Lupescu, PhD and Jared Faltys, CPA/PFS provide a current market update. Recorded October 16, 2026.
Category: Blog
Lemonade Camp – August 4th, 2026
Tuesday, August 4th, 2026, over 75 young entrepreneurs gathered to spend the day learning business skills, running their own lemonade stand and having fun! Despite the rainy day, the campers still raised over $1,000 to be donated to the Norfolk Kiwanis Group! 🍋
Norfolk’s annual Lemonade Camp, hosted by McMill CPAs & Advisors, Retirement Plan Consultants and Wealth Management, was a success again in 2026! Lemonade Camp has been held annually since 2011, so this year marked our fifteenth year of hosting Lemonade Camp! The camp invites kids to come learn business basics and apply those lessons to their own business, a lemonade stand! All money raised at Lemonade Camp is always donated back to the community.
Wealth Management Fall Newsletter 2026

THE FUTURE IS UNKNOWN, SO PLAN ACCORDINGLY
I saw a great Forbes article recently that reinforced the fragility of forecasting using a quarter century-old anecdote about the Pentagon changing the way they identify future threats. The change stemmed from a review of how quickly the geopolitical landscape evolves—yesterday’s adversaries can become tomorrow’s allies. Rather than focusing on one specific forecast, it was more prudent to be prepared for all possible outcomes.
This echoes what we often say at Dimensional: Plan, don’t predict. We all have views about what the future may bring: companies that will succeed, economies that will grow, markets that will take off. Markets set prices based in part on the aggregate of these expectations. So, market prices already represent a forecast of the future. However, some investors may let their personal forecasts drive their asset allocation decisions. Dogmatic adherence to forecasts dictates concentrated investments that fall short in the event the future differs from our predictions. Diversifying portfolios is a tacit admission that we don’t have a crystal ball. You reduce the range of outcomes by preparing for what you can’t see coming.
Country stock market returns are a good example of this. Going all-in on one country because you have a view on where their stocks are headed opens you up to a wide range of outcomes. The average difference between the best and worst performing developed market countries over the past two decades was over 50 percentage points. Get your call right, and you’ll look like a hero. Get it wrong, and you’ll be as apoplectic as when Chevy Chase’s character loses the rock, paper, scissors game in Vegas Vacation.
Article By: Wes Crill, PhD, Senior Client Solutions Director and Vice President at Dimensional Fund Advisors
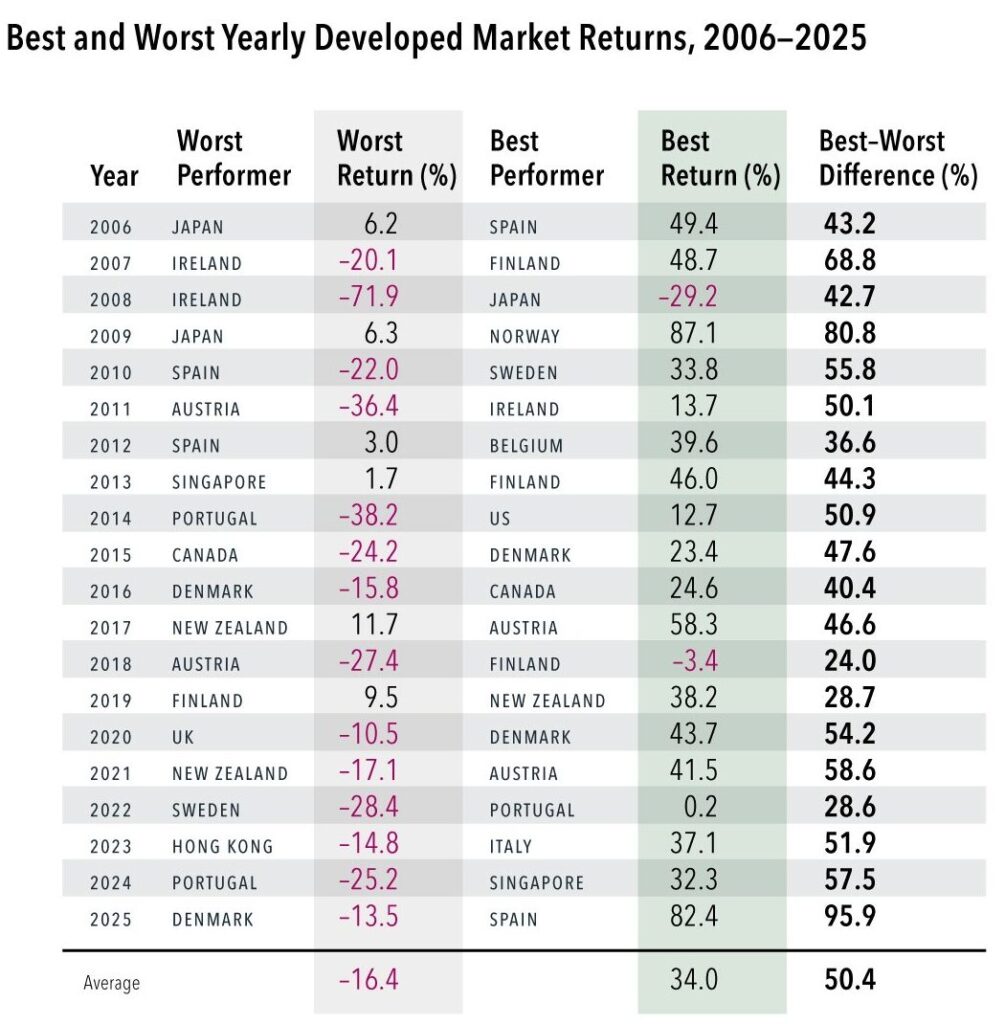
Past performance is not a guarantee of future results. Actual returns may be lower.
In USD. Indices are not available for direct investment; therefore, their performance does not reflect the expenses associated with the management of an actual portfolio. Diversification neither assures a profit nor guarantees against loss in a declining market. MSCI country indices (net dividends) for each country listed. MSCI data © MSCI 2026, all rights reserved.
All expressions of opinion are subject to change. This information is not meant to constitute investment advice, a recommendation of any securities product or investment strategy (including account type), or an offer of any services or products for sale, nor is it intended to provide a sufficient basis on which to make an investment decision. Investors should consult with a financial professional regarding their individual circumstances before making investment decisions. Diversification neither assures a profit nor guarantees against loss in a declining market.
Risks include loss of principal and fluctuating value.
Dimensional Fund Advisors LP is an investment advisor registered with the Securities and Exchange Commission.
Investment products: • Not FDIC Insured • Not Bank Guaranteed • May Lose Value
Dimensional Fund Advisors does not have any bank affiliates.
MARKET EFFICIENCY EXPLAINED: WHY STOCK PRICES BEHAVE THE WAY THEY DO
NVIDIA smashed records and analyst predictions in late May 2026 when the company announced quarterly revenue of $81.6 billion. You might have expected great news like this to send the AI chipmaker’s shares soaring. Instead, they fell. That seemingly illogical result illustrates one of the most important ideas in investing: market efficiency.
The concept, popularized by Nobel Prize-winning economist Eugene Fama, is often misunderstood to mean that markets price stocks perfectly. Some investors might point to market crashes, bubbles and dramatic daily swings as evidence that the efficient market hypothesis must be wrong. But that’s not what the hypothesis actually says. Instead, it states that asset prices reflect all available information about those assets. Understanding that distinction can help investors make better decisions—and perhaps avoid costly mistakes.
MARKETS PRICE THE FUTURE
The stock market is forward-looking: Stock prices are based on what investors collectively expect will happen in the future. Every trading day, millions of investors evaluate earnings reports, economic data, interest rates, new products, geopolitical events and countless other pieces of information. They use this data to constantly update expectations about a company’s future earnings and cash flows. The investments they make based on this new information collectively set the price of the company’s stock.
This constant incorporation of new information is why NVIDIA’s blockbuster report wasn’t enough to send the stock higher. Investors likely anticipated extraordinary results long before the company released them, and those expectations were already reflected in the stock price. When the news arrived, it fell short of what investors had already priced in.
In much of our lives, we’re comfortable with market prices. We rarely question the price of apples at the store, for example. We just assume that the price is what it needs to be, based on supply and demand. Stocks often inspire a different mindset. Many investors approach investing as if the assignment is to outsmart the market—finding hidden bargains or identifying tomorrow’s winner before anyone else does. Sometimes lightning strikes and the stock they pick jumps. But many investors wind up like the ones who bought shares of NVIDIA just before the quarterly announcement expecting an easy win, only to be sorely disappointed.
DON’T VOLATILITY AND BUBBLES PROVE MARKETS ARE INEFFICIENT?
Investors often ask, “If the market is so efficient, why is it so volatile? And how can the market be efficient when history is full of boom-and-bust cycles like the dot-com and real estate bubbles?”
In fact, volatility is exactly what you would expect from an efficient market. Markets are constantly digesting new information. When information changes rapidly, prices should adjust equally fast. Volatility is evidence that market expectations are responding to new data, not that they’re broken. What about bubbles? The efficient market hypothesis says prices reflect all available information. The problem during bubbles is that investors become overly optimistic about what that information means for the future.
A bubble doesn’t mean the market failed; it means investors collectively reached conclusions that turned out to be wrong.
MARKET EFFICIENCY HAS ITS LIMITS
Are markets perfectly efficient? Probably not—and that may be a good thing. Economists Sanford Grossman and Joseph Stiglitz famously identified what has become known as the Grossman-Stiglitz paradox: If markets were perfectly efficient all the time, no investor would have any incentive to spend time researching companies or uncovering new information. After all, if stock prices already reflected everything there is to know, there would be no reward for doing the work.
But if nobody gathered new information, markets would become less efficient over time. Markets need a small amount of inefficiency to motivate investors to seek out new information. Those efforts help keep prices reasonably accurate. Rather than viewing markets as perfectly efficient or hopelessly inefficient, it may be more useful to think of them as highly competitive systems that are constantly moving toward efficiency, even if they never fully arrive there.
WHAT DOES THIS MEAN FOR INVESTORS?
While markets may not be perfectly efficient, you may be better off investing as though they are. Why? To outsmart the market, you would need to have meaningful information no one else has. In 2025, more than 17 billion shares worth more than $1 trillion traded in the U.S. every day, on average. Those trades were conducted by institutional investors, hedge funds, quantitative trading firms, analysts, economists, sophisticated computer models and professional investors around the world, all competing to identify opportunities before everyone else. Finding something they’ve missed may not be impossible, but it’s vanishingly unlikely.
The belief that markets can be outsmarted can lead to counterproductive behaviors. One of the most dangerous is market timing. This is the strategy of making decisions on whether to buy or sell financial assets by attempting to predict future market prices. History suggests timing the market is remarkably difficult to do consistently. Studies have repeatedly found that the average equity investor’s returns tend to trail the S&P 500, largely because poor timing decisions caused them to buy after markets had already risen and sell after markets had already fallen.
Accepting the idea of market efficiency can be surprisingly liberating. During periods of high volatility or big market drops, you can rest assured that the market is doing exactly what it’s supposed to be doing as it incorporates new information. Rather than chasing headlines or trying to predict every market move, you can focus on what you can control: maintaining a diversified portfolio, sticking to a long-term investment plan, keeping costs low, and allowing compounding to work over time. If you have any questions about market efficiency or your portfolio, please don’t hesitate to reach out.
sources: https://nvidianews.nvidia.com/news/nvidia-announces-financial-results-for-first-quarter-fiscal-2027
https://www.google.com/finance/beta/quote/NVDA:NASDAQ?window=YTD
https://www.chicagobooth.edu/review/eugene-fama-efficient-markets-and-the-nobel-prize
https://www.aeaweb.org/aer/top20/70.3.393-408.pdf
https://www.cboe.com/insights/posts/2025-u-s-equities-year-in-review/
https://www.dalbar.com/press-release/dalbars-2026-qaib-report-shows-narrower-investor-gap-amid-a-complex-and-volatile-market-year/
PREPARING FOR MEDICARE: WHAT YOU NEED TO KNOW BEFORE YOU TURN 65
Most people spend decades saving, investing and planning for retirement. But one of the biggest financial decisions of your retirement years has little to do with your portfolio. Rather, it has to do with a government program, an important birthday and a deadline you really don’t want to miss.
That program is Medicare, and you have a short window around your 65th birthday to sign up. Doing so will help you take full advantage of all that Medicare has to offer and give you more flexibility as you navigate healthcare spending in retirement. Here we’ll explain what you need to know about your Medicare benefits and how to prepare.
SIGNING UP FOR MEDICARE
Medicare was created in 1965 to ensure seniors have access to affordable healthcare in retirement. While it isn’t free, you’ve likely already paid for a big chunk of it through decades of payroll taxes—a compelling reason to start taking advantage of your benefits as soon as you’re eligible.
The enrollment window opens three months before the month of your 65th birthday and closes three months after. If you don’t enroll during your Initial Enrollment Period, you could face coverage delays and higher monthly premiums for the rest of your life. These penalties are designed to discourage people from waiting until they get sick to buy coverage. You can enroll and choose plans on the Social Security website.
Note that seniors who continue to receive private health insurance through an employer might be exempt from Medicare enrollment obligations and penalties. It depends on the company’s size and plan details. Let’s take a closer look at each part of Medicare, and what you need to consider.
PART A: HOSPITAL COVERAGE
Part A covers inpatient hospital stays, skilled nursing facility care, hospice services and some home healthcare. For most people, there’s no monthly premium. That’s because Part A is what you funded through payroll deductions, assuming you or your spouse contributed for at least 10 years. But you will be responsible for deductibles: $1,736 in 2026 for the first 60 days of a hospital stay, with substantial copayments beyond that.
Assuming you have paid into Medicare through your lifetime earnings, there’s no financial penalty for delaying Part A enrollment—but also no reason not to enroll.
PART B: OUTPATIENT COVERAGE
Part B covers outpatient services, including emergency room and doctor visits, preventive care, lab work and medical equipment. In 2026, standard monthly premiums for Part B are $202.90, and they can be higher, depending on your income and filing status. There is also an annual deductible of $283, plus a 20% copay for most doctor visits.
Missing your Initial Enrollment Period will add a permanent 10% surcharge to your Part B premium for every full 12-month period delayed.
PART C: MEDICARE ADVANTAGE
Part C, commonly known as Medicare Advantage, refers to optional plans offered by private insurers that combine Parts A and B and sometimes Part D. Part C plans offer lower out-of-pocket costs and have fixed copays for office visits (instead of 20% for Part B), with smaller or no annual deductibles. By law, they must include a maximum annual out-of-pocket cost, which varies depending on whether you see doctors in or outside the plan’s network. The plans may also include benefits like dental, vision and hearing.
When you sign up for Part C, you’ll still need to pay your Part B premium. While you might need to pay an additional premium on top of that, some Medicare Advantage plans charge no additional premium. Television advertising makes it sound like Medicare Advantage plans provide all kinds of extra money for buying groceries, etc.; however, you need to be careful as to where you will be retiring and whether doctors or hospitals you plan to see are covered by Part C. Many rural area hospitals do not accept Medicare Part C. Even though these plans are referred to as Advantage plans, there are some disadvantages to them.
PART D: PRESCRIPTION DRUG COVERAGE
Part D covers prescription drugs, with plans offered through private insurance companies. In 2026, the average monthly Part D premium is $34.50, but it varies based on the plan details and where you live. You may also pay an annual deductible (in 2026, up to $615) and co-insurance on each prescription, which can vary depending on the drug’s “tier” or pricing scale. Note that most Medicare Advantage plans also include Part D coverage.
You won’t have to pay for Part D if you have creditable drug coverage already (from a current employer, for instance) or qualify for extra help. Otherwise, you are required to have Part D, and delaying enrollment will add a permanent 1% surcharge to your premium for every month delayed. There is a period of time each year when you can change the Part D provider. It is wise to check this out, because premiums and net costs for drugs do change each year along with possible changes in your prescriptions.
MEDIGAP: THE FINAL PIECE OF THE PUZZLE
Medigap policies are supplemental private policies that help pay out-of-pocket costs for Parts A and B. They charge higher premiums, sometimes several hundred dollars more a month. However, they fill in the gaps of what isn’t covered by Parts A and B.
You can’t have both Medigap and Medicare Advantage. The Medigap enrollment period is six months beginning the first day you are 65 and have Part B coverage. Enroll in this period and you can’t be denied coverage based on preexisting conditions.
Medicare has a lot of moving parts, and we can help you unpack them. If you have any questions, reach out. After all, understanding Medicare—and when to sign up for what—is good for your health and wealth. With smart preparation, you’ll almost certainly pay less for healthcare in retirement, even as your medical needs grow.
sources:https://www.cms.gov/about-cms/who-we-are/history
https://www.ssa.gov/medicare/sign-up
https://www.cms.gov/newsroom/fact-sheets/2026-medicare-parts-b-premiums-deductibles
https://www.medicare.gov/basics/costs/medicare-costs
https://www.ncoa.org/article/medicare-advantage-medicare-part-c-costs/
https://www.cms.gov/newsroom/press-releases/medicare-advantage-medicare-prescription-drug-programs-expected-remain-stable-2026
https://www.medicare.gov/health-drug-plans/part-d/basics/costs
https://www.medicare.gov/basics/costs/medicare-costs/avoid-penalties
WE ARE HERE TO HELP
“We are here to help.” We often say this in our articles and letters that we provide you with. We are not saying that we will make decisions for you, but we will try to help provide valuable information so that you can make an informed decision. There is a lot of information floating around out there, and we try to discern what is the proper information for you and your situation.
So let us know if you have any concerns or questions. We are here to help. Have a great fall!
Investments provided through McMill Wealth Inc, a Nebraska Corporation, Registered Investment Advisor
This material is derived from sources believed to be reliable, but its accuracy and the opinions based thereon are not assured.
The articles and opinions in this publication are for general information only and are not intended to serve as specific financial, accounting or tax advice
WEBINAR (7/16/2026) – NAVIGATING THE MARKETS – 2ND QUARTER SUMMARY
Dimensional Fund Advisors Vice President, Apollo Lupescu, PhD and Jared Faltys, CPA/PFS provide a current market update. Recorded July 16, 2026.
Wealth Management Summer Newsletter 2026
A GUIDE TO THOUGHTFUL SPENDING
It has never been more tempting to spend money. Every day, we’re pressured to buy something, whether through traditional ads, targeted recommendations or the curated lifestyles of online influencers. The messages are constant and persuasive.
Financial professionals like us spend a lot of time talking about how to save. But knowing how to spend well is equally important. And for many, spending is surprisingly fraught, wrapped up in behavioral biases and the psychological imprints of past experiences.
Unexamined spending can lead to extremes. On one end of the spectrum, you find overspenders who rack up debt and land in financial hot water. On the other end are those afraid to spend, depriving themselves of things they can afford that would give them pleasure.
Ultimately, spending is unavoidable. Ideally, we find a middle path that allows us to cover necessities and spend on the things that truly bring joy, whether that’s hobbies, travel, experiences with your family and friends, or simple everyday pleasures.
So how do you engage in thoughtful spending? These tips can help.
CONSIDER YOUR VALUES
One of the best ways to become a mindful spender is to spend in line with your values. Take the time to identify what matters most to you. These could be things like health, family, community, security or creativity. Before making a purchase, consider whether it supports one or more of these values. Doing so can help you avoid potential behavioral traps, such as signaling—spending money to shape how other people think of us.
It’s one thing to buy a nicer car because you need it. It’s another to buy one because you want to broadcast status to neighbors.
If you can truly afford to do this, there’s not necessarily a lot of harm done financially speaking. But it’s still worth asking whether the motivation reflects something you truly value or simply a desire to impress others.
And if the purchase stretches your finances, the irony is clear: Spending to appear wealthy actually undermines your financial security.
COMPARE AND DESPAIR
Closely related to signaling is the phenomenon of keeping up with the proverbial Joneses.
Morgan Housel, partner at The Collaborative Fund and author of The Psychology of Money puts it well: “There are two ways to use money. One is as a tool to live a better life. The other is as a yardstick of status to measure yourself against others. Many people aspire for the former but get caught up chasing the latter.”
When we see other people spending freely—neighbors renovating their kitchen or friends taking pricey vacations—it can create subtle pressure to match their choices. After all, we humans are deeply wired to avoid appearing like outsiders.
But appearances can be misleading. The people you’re comparing yourself to may be financing those purchases or stretching their budget to maintain a perfect front.
So again, before trying to match anyone’s spending, revisit your own priorities. You may find that the security of living within your means is much more important to you.
BE MINDFUL OF HEDONIC ADAPTATION
Besides being a bit of a mouthful, hedonic adaptation is the tendency for humans to return to a baseline level of happiness even after major positive or negative changes in their lives. In other words, the emotional impact of these events fades quickly over time.
This can have important implications for spending. Many purchases—the latest smartphone, a luxury car, a bigger home—promise lasting happiness. These items might provide a short-term boost in satisfaction, but that feeling typically fades faster than we’d expect.
Understanding this tendency can encourage a bit of pause before making big purchases. If it’s greater happiness you seek, whatever you’re considering buying likely isn’t the solution.
Being mindful of hedonic adaptation can also help guard against lifestyle creep, where spending gradually increases as income rises without necessarily improving long-term happiness. Buying that bigger home requires spending more on things like taxes and upkeep, which may quickly make you feel out of control. Or as Housel puts it: “Sometimes the stuff you spend money on has so much influence over your autonomy…that it’s not clear whether you own things or the things own you.”
On a more reassuring note, just as we adapt to positive changes, we also adapt to setbacks. Difficult events like a job loss or a financial downturn can feel overwhelming in the moment, but emotional recovery tends to be swift.
THINK BEFORE YOU CARPE DIEM
Popular aphorisms encourage us to “carpe diem,” “YOLO” or “live for the moment.” And on a fundamental level, that message has merit. Life is unpredictable, and it’s important to enjoy it. However, the idea also can be used to justify impulsive spending, allowing our present selves to win out over our future selves.
Consider a simple example: Spending $200 on a new pair of boots now may not seem like a major decision. However, if that same amount were invested and allowed to grow for decades, it could be worth thousands of dollars in the future.
This doesn’t mean you should never buy those boots—especially if you can afford them. The key is considering the trade-off and making that decision consciously.
Interestingly, carpe diem—often translated as “seize the day”—may have originally carried a more nuanced meaning. Some scholars suggest it would be better translated as “pluck the day,” an allusion to picking fruit or flowers at harvest time. Seen this way, the phrase originally may be more about appreciation and enjoying opportunities when the moment is right, rather than an exhortation to take impulsive action. That, perhaps, is a useful way to think about spending as well.
A PLAN THAT MAKES ROOM FOR LIVING
It might be easy to think that financial advice is all about pushing you to cut back and save more. In reality, it’s about finding balance. Together, we can build spending strategies that reflect what matters to you most, so you can feel confident about your future without putting your present happiness on hold.
MARKET RETURNS DURING PAST GEOPOLITICAL CONFLICTS
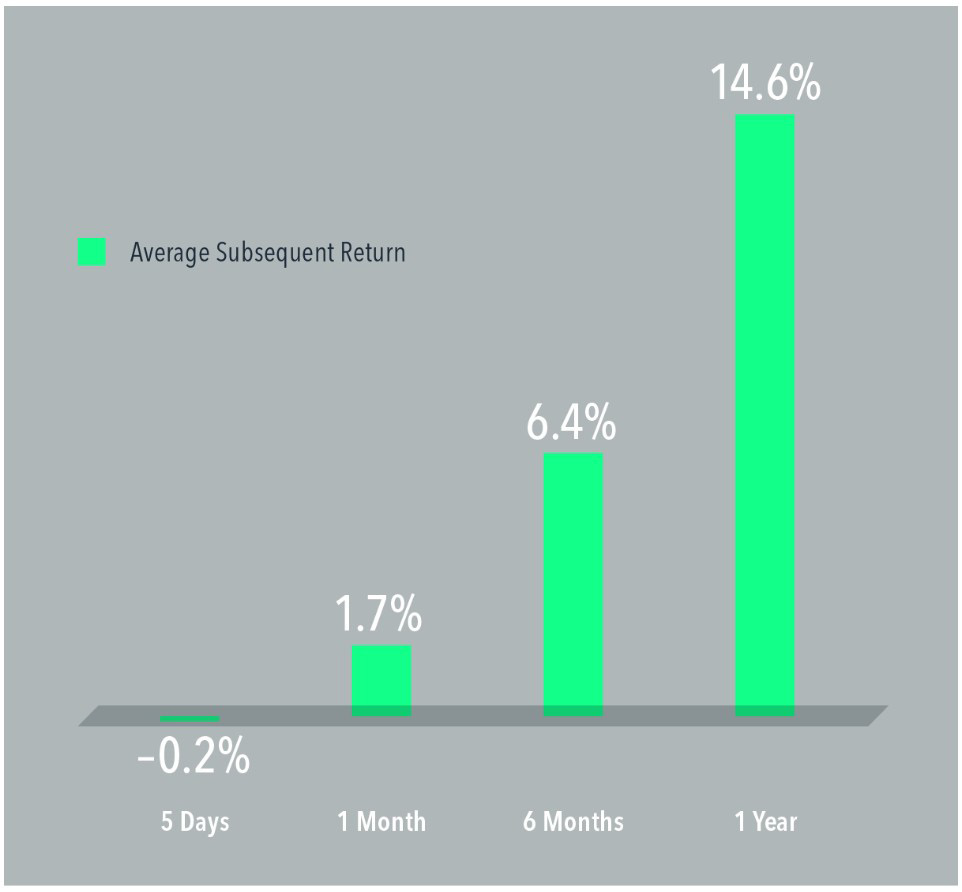
We noted in a recent piece that geopolitical conflicts don’t have to result in disappointing subsequent stock returns because markets are forward-looking and set prices for positive expected returns. But how have markets actually fared during previous geopolitical incidents? Based on 36 years of history, the answer has largely been good news.
While the classification of an event as a geopolitical conflict is subjective, we identified 21 global events since 1990. Charting returns starting from the onset of these events, we see slightly negative returns on average for the first five days, but then positive average returns over subsequent horizons. This would seem consistent with a market resetting prices in light of negative news at the start, which then sets up a positive expected return in the absence of further disappointing developments. After one year, the average return was 14.6%. By comparison, the average return across all rolling 12-month periods was 12.4%.
This is not to imply we’re “out of the woods” when it comes to a market downturn. The 12-month market return was negative for two of the 21 events. There’s always the possibility for worse-than-expected developments, which might provoke further negative reaction from markets. But the takeaway from these data is that investors shouldn’t shy away from stocks during a period of global conflict.
Exhibit 1
Average US Stock Market Returns Following Major Geopolitical Events
1990-2025
Article By: Wes Crill, PhD
Senior Client Solutions Director and Vice President at Dimensional Fund Advisors
See below for disclosures.
THE LEGACY CONTINUES
Again, as usual many made their annual voyage to Omaha, Nebraska for this year’s annual meeting for Berkshire Hathaway which was held on May 2nd, 2026 to see what changes, if any, might be taking place or are on the horizon. This was the first year that Warren Buffett was not the CEO of Berkshire Hathaway, and this year’s annual shareholders’ meeting was conducted by Greg Abel, Warren Buffett’s hand-picked successor. The theme of this year’s meeting was “the legacy continues” which was evident from what Greg Abel explained about how the company was to be run under his leadership. It did not take long to surmise that Greg Abel is very knowledgeable and plans to do things by the “manual” developed by Warren Buffett on how to run the business. Even though Warren Buffett is no longer the CEO of Berkshire Hathaway, he is the Chairman of the Board and goes to the office 5 days per week to render his advice and help in an advisory capacity.
Warren was present for the shareholders’ meeting (sitting with the other Board members) and spoke on a couple of occasions. During his talks, he stressed that investing should be treated as “investing” not “gambling”. Investing is for the long-term—not a way to turn a quick buck. He also talked about his management style which was to abide by the “Golden Rule”—treating others the way that you want to be treated yourself. “Integrity” was stressed at the meeting by Greg Abel as to how the company will be run in the future.
To begin the question-and-answer period, an AI-created deepfake of Warren Buffett was used to ask a question about how a person like him, being 95 years old, should look at investing. This situation was shown for everyone to see how careful you must be with the use of AI, and how you need to question if you are dealing with reality or if it is “fake”. The deepfake appeared to be very real to show how you can be easily fooled. AI can be a very helpful tool, but must be carefully scrutinized.
Market Returns During Past Geopolitical Conflicts disclosures:
Past performance is not a guarantee of future results. Actual investment returns may be lower. In USD. US Market is represented by the Fama/French Total US Market Research Index. The Fama/French indices represent academic concepts that may be used in portfolio construction and are not available for direct investment or for use as a benchmark. See “Index Descriptions” for descriptions of the Fama/French index data. Indices are not available for direct investment. Their performance does not reflect the expenses associated with the management of an actual portfolio. The chart is for illustrative purposes only and is not indicative of any investment. The sample includes 21 geopolitical events. Geopolitical events and their start dates include: Gulf War, August 2, 1990; Asian currency crisis, July 2, 1997; 1998 Iraq disarmament crisis, February 18, 1998; Russian Financial Crisis, August 17, 1998; Kosovo bombings, March 24, 1999; 9/11—terrorist attacks on the United States, September 11, 2001; Iraq War, March 20, 2003; Madrid bombings, March 11, 2004; London bombings, July 7, 2005; Iran nuclear tensions, July 31, 2006; Eurozone debt crisis, December 8, 2009; Arab Spring (Egypt), January 25, 2011; Libya intervention, March 19, 2011; 2014 Ukraine conflict, February 20, 2014; intervention in Syria, September 22, 2014; Paris attacks, November 13, 2015; Brexit vote, June 23, 2016; air strike on Syrian air base, April 7, 2017; North Korea nuclear test, September 3, 2017; Russia invades Ukraine, February 21, 2022; Israel-Hamas conflict, October 7, 2023. Events are selected to include major armed conflicts and notable upheavals and are not inclusive of all possible market events.
Expected return: An estimate of average anticipated returns informed by historical data.
Fama/French Total US Market Research Index: July 1926–present: Fama/French Total US Market Research Factor + One-Month US Treasury Bills.
Results shown during periods prior to each index’s inception date do not represent actual returns of the respective index. Other periods selected may have different results, including losses. Backtested index performance is hypothetical and is provided for informational purposes only to indicate historical performance had the index been calculated over the relevant time periods. Backtested performance results assume the reinvestment of dividends and capital gains. Eugene Fama and Ken French are members of the Board of Directors of the general partner of, and provide consulting services to, Dimensional Fund Advisors LP. The information in this material is intended for the recipient’s background information and use only. It is provided in good faith and without any warranty or representation as to accuracy or completeness. Information and opinions presented in this material have been obtained or derived from sources believed by Dimensional to be reliable, and Dimensional has reasonable grounds to believe that all factual information herein is true as at the date of this material. It does not constitute investment advice, a recommendation, or an offer of any services or products for sale and is not intended to provide a sufficient basis on which to make an investment decision. Before acting on any information in this document, you should consider whether it is appropriate for your particular circumstances and, if appropriate, seek professional advice. It is the responsibility of any persons wishing to make a purchase to inform themselves of and observe all applicable laws and regulations. Unauthorized reproduction or transmission of this material is strictly prohibited. Dimensional accepts no responsibility for loss arising from the use of the information contained herein. This material is not directed at any person in any jurisdiction where the availability of this material is prohibited or would subject Dimensional or its products or services to any registration, licensing, or other such legal requirements within the jurisdiction.
“Dimensional” refers to the Dimensional separate but affiliated entities generally, rather than to one particular entity. These entities are Dimensional Fund Advisors LP, Dimensional Fund Advisors Ltd., Dimensional Ireland Limited, DFA Australia Limited, Dimensional Fund Advisors Canada ULC, Dimensional Fund Advisors Pte. Ltd., Dimensional Japan Ltd., and Dimensional Hong Kong Limited.
RISKS – Investments involve risks. The investment return and principal value of an investment may fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original value. Past performance is not a guarantee of future results. There is no guarantee strategies will be successful.
UNITED STATES – Dimensional Fund Advisors LP is an investment advisor registered with the Securities and Exchange Commission.
Investment products: • Not FDIC Insured • Not Bank Guaranteed • May Lose Value
Dimensional Fund Advisors does not have any bank affiliates.
Investments provided through McMill Wealth Inc, a Nebraska Corporation, Registered Investment Advisor
This material is derived from sources believed to be reliable, but its accuracy and the opinions based thereon are not assured.
The articles and opinions in this publication are for general information only and are not intended to serve as specific financial, accounting or tax advice
WEBINAR (5/1/2026) – NAVIGATING THE MARKETS – 1ST QUARTER SUMMARY
Dimensional Fund Advisors Vice President, Apollo Lupescu, PhD and Jared Faltys, CPA/PFS provide a current market update. Recorded May 1, 2026.
Wealth Management Spring Newsletter 2026
MARKET REVIEW 2025: US STOCKS RIDE ROCKY ROAD TO A THIRD STRAIGHT YEAR OF GAINS
KEY TAKEAWAYS
• US stocks continued climbing in 2025, with the S&P 500 gaining almost 18%, while international stocks soared nearly 32%.
• The Fed reduced interest rates by 0.75 percentage points even as it coped with stubborn inflation, citing labor market worries.
• Value lagged growth in the US, but international small value was among the best-performing asset classes of the year.
US stocks notched their third year in a row of double-digit gains, but it wasn’t the smoothest ride. The S&P 500 hit records in the winter that were followed by a spring swoon. After powering past that to new highs in the fall, the markets cooled a bit along with the temperatures.(1) Still, the S&P 500 was up 17.9% for the year and closed near record levels.(2) The climb came despite tariff uncertainty, interest rate changes, and concerns about the durability of AI’s gains—not to mention the longest government shutdown in US history.(3) Global stocks rose (see Exhibit 1), with returns in developed international and emerging markets better than those in the US. In the bond market, US Treasuries were higher for the year, and the benchmark 10-year yield fell to just above 4%.(4)
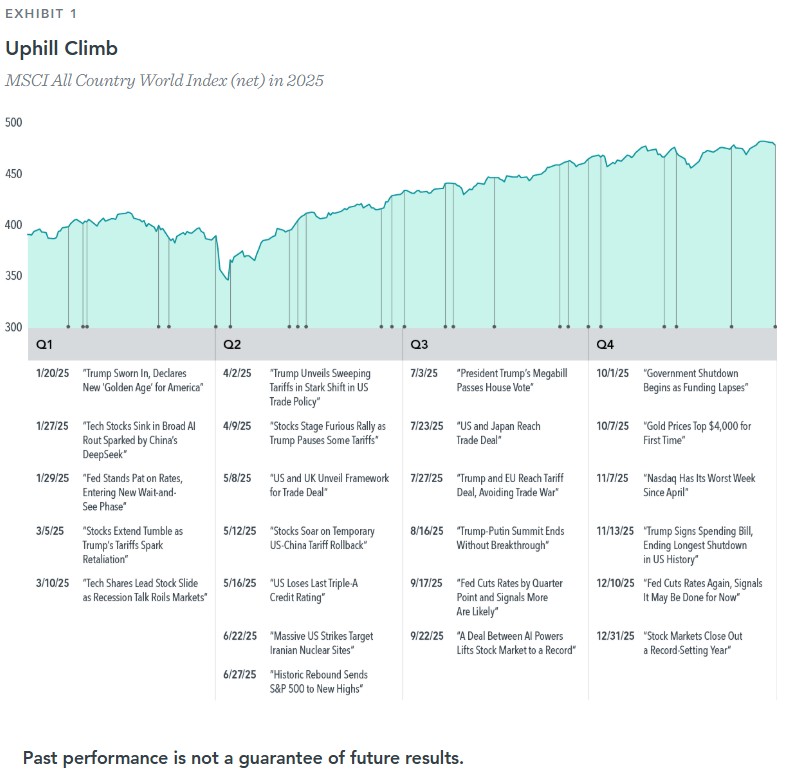
Technology companies were below earlier highs at year’s end, but the tech-heavy Nasdaq still advanced 20.9% in 2025. Just months after reaching $4 trillion, NVIDIA became the first public company to reach a market capitalization of $5 trillion, though it wouldn’t hold that level. The headline names associated with artificial intelligence have been strong performers in recent years.(5) But diversified equity portfolios don’t need to chase a few big names to have exposure to AI—the technology touches many types of businesses. Broad diversification can help investors avoid missing out on these winners, wherever they show up.
The US Federal Reserve cut the federal-funds rate by a quarter point three times, in September, October, and December, to a range between 3.5% to 3.75%, the lowest level in three years.(6) In its December statement, the Fed cited labor-market worries as it lowered rates while also noting rising inflation and that not all members supported the rate decrease. But while investors may worry about the impact of Fed rate changes, market interest rates and the federal-funds rate don’t always move as one—the 10-year Treasury yield, for example, hasn’t always gone in the same direction as the fed-funds rate.
Market fluctuations coincided with trade talks throughout the year, most notably with the global tariff announcement from the US in April, after which stocks took a downward turn. But as tariffs were delayed and talks progressed—and with the US reaching a number of trade deals—the market rebounded.(7) Still, questions remained about tariffs elsewhere. In a high-stakes case, the Supreme Court appeared skeptical about the legality of tariffs but has yet to rule on whether any recently imposed levies can remain in place.(8) Adding to uncertainty late in the year, the government shut down in October and November for 43 days. But markets continued to post gains, as they often have during extended closures. Congress reached a deal in mid-November to reopen the government, but only through the end of January.(9)
LOOKING ABROAD
In a departure from recent years, developed international stocks fared better than their US counterparts. The MSCI World ex USA Index gained 31.9%, outpacing the S&P 500 by the widest margin since 1993 and serving as a reminder of the potential benefits of an internationally diversified portfolio. Emerging markets fared even better than developed markets, with the MSCI Emerging Markets Index rising 33.6%. Global equities, as measured by the MSCI All Country World Index, rose 22.3% for the year.(10)
Developed market international stocks outdid their US counterparts by the widest margin since 1993.
Likewise, investors who targeted value stocks outside the US were rewarded; however, value lagged growth in the US. Large caps outperformed small caps in the US and globally, but international small value was among the best-performing asset classes of the year. Longer term, US small value has been one of the best-performing asset classes since 2000. That has included a period of strong performance for the large cap S&P 500: Over the past 10 years, it returned 14.8% annually. That’s a notable deviation from large caps’ long-term average, whereas the returns of small caps have been more in line with their historical performance over that same period. Elsewhere, high profitability stocks were outpaced by low profitability stocks in global developed markets in 2025, while the opposite was true in emerging markets.(11)
In the bond market, US Treasuries returned 6.3%, sending the yield on the benchmark 10-year Treasury down to 4.18%.(12) The broader bond market also posted gains during the year, with the Bloomberg US Aggregate Bond Index up 7.3%, its best annual return since 2020. The Bloomberg Global Aggregate Bond Index (hedged to USD)—a broad benchmark of sovereign and corporate debt—rose 4.9% for the year.(13)
Investors showed increased appetite for gold in 2025, pushing prices up more than 50% to above $4,000 per ounce for the first time.(14) Some market participants view gold as a hedge during economic downturns or against inflation. But since 1970, gold has often experienced large price swings relative to annual inflation. Over the same period, gold prices showed little relation to fluctuations in the US GDP. Whether gold was up or down doesn’t appear connected to what was happening in the economy. Since markets tend to reflect expectations for the economy in advance, it’s not clear holding gold provides additional protection against adverse economic developments.
MIND OVER MATTERS
A better way to cope with market volatility may be to simply pay less attention. Just this past year, if you had gone to sleep on April Fools’ Day and checked your investment portfolio a month later, you might have assumed the market had been relatively calm. But for investors who spent the month tracking daily returns, the experience likely felt more disruptive. April 2025 turned out to be one of the most volatile months in recent history, as market participants were processing new information about tariffs and trying to make sense of what the developments might mean for businesses, investors, and the global economy.
The same thinking can guide investors’ approach over longer time periods—especially when looking at data across many years or even decades. With reliable stock data stretching back to 1926, we are, as of this year, now able to consider a full century of stock returns. Doing so gives further credence to the merits of focusing on the long run. A short-term view of yearly gains and losses shows what may appear as wild swings in the market, as seen in Exhibit 2, but a long-term view reveals a fairly steady growth of wealth over the 100-year period.
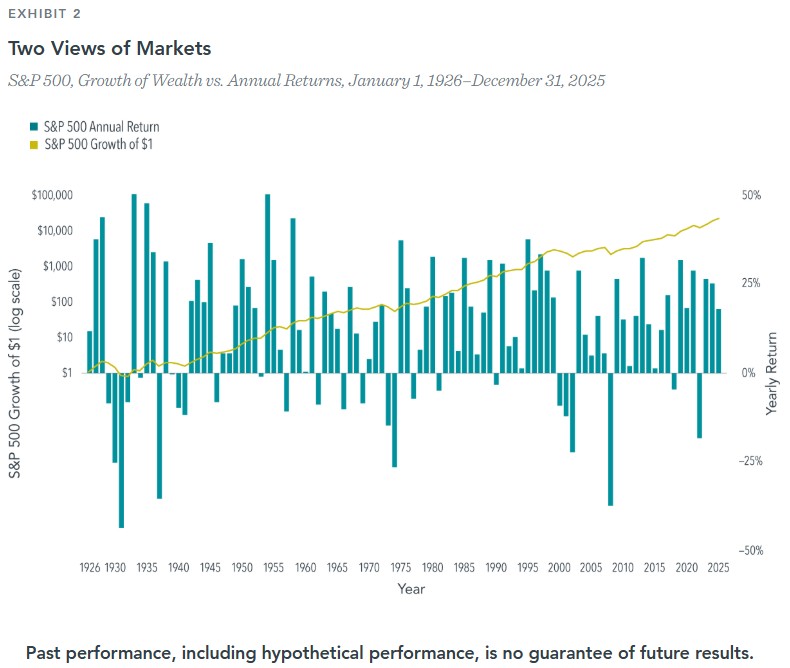
It is natural to want to stay informed about what’s going on in the world. And when markets are volatile, it may be hard to resist the urge to do something. But doing nothing can be a fine course of action. Thinking about investments over the long term might ease the urge to make hasty asset allocation changes. An investor who stayed the course over the long term—riding out the ups and downs of economic shocks, wars, and other crises—would have seen exponential gains in their investment. Declines can be painful in the moment, but markets have shown resilience throughout history. Last year was another example: Investors who stayed in their seats were in a great position to be rewarded.
Article By: Dimensional Fund Advisors
Footnotes:
1. Joe Rennison, “Late Rally Pushes Stocks Back Near Record High,” The New York Times, November 28, 2025.
2. S&P data © 2025 S&P Dow Jones Indices LLC, a division of S&P Global. All rights reserved. Indices are not available for direct investment. Their performance does not reflect the expenses associated with the management of an actual portfolio; Ben Levisohn, “S&P 500 Hits a Rare Christmas Eve Record,” Barron’s, December 24, 2025.
3. Martin Baccardax, “One Earnings Report Can’t Erase the Stock Market’s AI Bubble Concerns,” Barron’s, November 20, 2025; Rachel Treisman, “The Government Shutdown Is Now the Longest in US History. See How It Compares,” NPR, November 5, 2025.
4. Returns are based on the Bloomberg US Treasury Bond Index as of December 31. Bloomberg data is provided by Bloomberg Finance LP. Source for US Treasuries: US Department of the Treasury.
5. Cade Metz, “The AI Boom Has Found Another Gear. Why Can’t People Shake Their Worries?” The New York Times, November 20, 2025.
6. The federal-funds rate is the overnight interest rate at which one depository institution (like a bank) lends to another institution some of its funds that are held at the Federal Reserve. Source: “Federal Reserve Issues FOMC Statement,” US Federal Reserve, December 10, 2025.
7. Chao Deng and Drew An-Pham, “What to Know About Trump’s Latest Tariffs,” The Wall Street Journal, October 30, 2025.
8. Lawrence Hurley, “Supreme Court Appears Skeptical of Trump’s Tariff Argument,” NBC News, November 5, 2025.
9. Kaia Hubbard and Caitlin Yilek, “Government Shutdown Now Over as Federal Agencies Reopen and Employees Return to Work,” CBS News, November 13, 2025.
10. MSCI data © MSCI 2025, all rights reserved. Indices are not available for direct investment. Their performance does not reflect the expenses associated with the management of an actual portfolio.
11. The MSCI World ex USA Value Index gained 42.2%, while the MSCI World ex USA Growth Index rose 21.9% as of December 31, 2025; the Russell 3000 Value Index added 15.7%, while the Russell 3000 Growth Index rose 18.2%; the Russell 2000 Index added 12.8%, while the Russell 1000 Index gained 17.4%; the MSCI All Country World Small Cap Index advanced 19.7%, while the larger cap MSCI All Country World Index rose 22.3%; the MSCI World ex USA Small Value Index was up 38.6% as of December 31, 2025; the Fama/French Developed High Profitability Index rose 19.3% versus 30.0% for its low profitability counterpart as of December 31, 2025; the Fama/French Emerging Markets High Profitability Index rose 32.6%, and its low profitability counterpart rose 20.8% as of December 31, 2025. Past performance is no guarantee of future results. Actual returns may be lower. The Fama/French indices represent academic concepts that may be used in portfolio construction and are not available for direct investment or for use as a benchmark. Index returns are not representative of actual portfolios and do not reflect costs and fees associated with an actual investment. See “Index Descriptions” in the Appendix for descriptions of the Fama/French index data.
12. “Daily Treasury Par Yield Curve Rates,” US Department of the Treasury. Data as of December 31, 2025.
13. Bloomberg data provided by Bloomberg Finance LP. Data as of December 31, 2025.
14. Spencer Kimball, “Gold Price Reaches $4,000 an Ounce for the First Time Ever,” CNBC, October 7, 2025.
Please see below for additional disclosures
WHY NOW MAY BE A GOOD TIME TO REVISIT YOUR SILVER COLLECTION
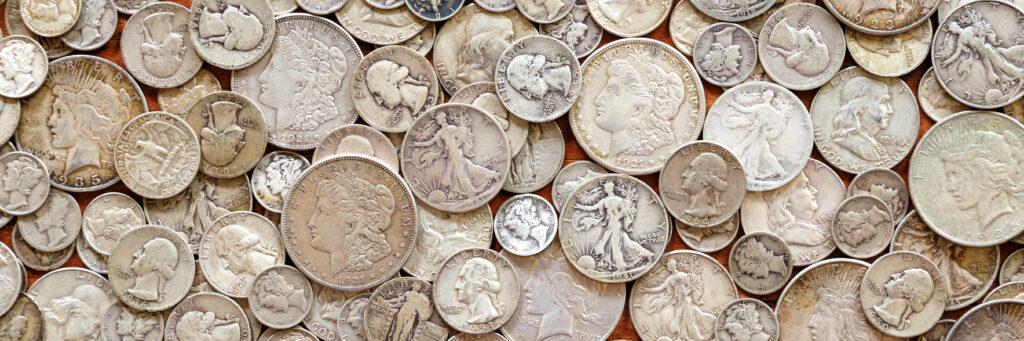
Investing isn’t always about what you buy. Sometimes it’s about recognizing when something no longer needs to be held. We typically see gold dominating the headlines, but current conditions have shifted the focus to silver. Silver has multiple roles, both as a monetary metal and a key component in technology items, including solar panels, cell phones, electric vehicles and items in healthcare.
During the holidays, silver was in the middle of a strong run. While visiting my parents, I asked my dad about a stash of bulk silver coins he’d been holding for years. Most of them came from my uncle’s estate and had been sitting in a closet, untouched.
Selling doesn’t have to mean selling everything. We kept the coins that had sentimental or collector value. The rest were simply silver. After checking prices with a couple of dealers, we sold them locally at a price tied to the COMEX market. It’s always a good idea to obtain multiple appraisals and work with reputable and established dealers.
The value ended up being nearly three times what it would have been a year earlier. Instead of letting the gains sit idle, the proceeds were used to fund 529 plans for the grandkids.
This wasn’t a market call or a prediction. It was just a reminder that assets don’t exist in a vacuum. Their purpose matters. Turning something that had already appreciated into future education costs felt like a reasonable trade.
Conditions can shift quickly, so it’s worth occasionally taking inventory — not just of your portfolio, but of the things you own that have quietly become investments.
Article By: Nate Raabe
Market Review 2025: US Stocks Ride Rocky Road to a Third Straight Year of Gains disclosures continued:
Appendix
Index Descriptions: Results shown during periods prior to each index’s inception date do not represent actual returns of the respective index. Other periods selected may have different results, including losses. Backtested index performance is hypothetical and is provided for informational purposes only to indicate historical performance had the index been calculated over the relevant time periods. Backtested performance results assume the reinvestment of dividends and capital gains. Profitability is measured as operating income before depreciation and amortization minus interest expense scaled by book. Eugene Fama and Ken French are members of the Board of Directors of the general partner of, and provide consulting services to, Dimensional Fund Advisors LP.
Fama/French Developed High Profitability Index: Provided by Fama/French from Bloomberg data. Includes stocks in the upper 30% operating profitability (OP) range in each region; companies weighted by float-adjusted market cap. Rebalanced annually in June. OP for June of year t is annual revenues minus cost of goods sold; interest expense; and selling, general, and administrative expenses, divided by book equity for the last fiscal year-end in t – 1.
Fama/French Emerging Markets High Profitability Index: July 1991–present: Fama/French Emerging Markets High Profitability Index. Courtesy of Fama/French from Bloomberg and IFC securities data. Includes stocks in the upper 30% operating profitability range in each country; companies weighted by float-adjusted market cap; rebalanced annually in June. OP for June of year t is annual revenues minus cost of goods sold; interest expense; and selling, general, and administrative expenses, divided by book equity for the last fiscal year-end in t – 1.
Fama/French Total US Market Research Index: July 1926–present: Fama/French Total US Market Research Factor + One-Month US Treasury Bills. Source: Ken French website.
Disclosures: This information is intended for educational purposes and should not be considered a recommendation to buy or sell a particular security. Named securities may be held in accounts managed by Dimensional.
The information in this material is intended for the recipient’s background information and use only. It is provided in good faith and without any warranty or representation as to accuracy or completeness. Information and opinions presented in this material have been obtained or derived from sources believed by Dimensional to be reliable, and Dimensional has reasonable grounds to believe that all factual information herein is true as at the date of this material. It does not constitute investment advice, a recommendation, or an offer of any services or products for sale and is not intended to provide a sufficient basis on which to make an investment decision. Before acting on any information in this document, you should consider whether it is appropriate for your particular circumstances and, if appropriate, seek professional advice. It is the responsibility of any persons wishing to make a purchase to inform themselves of and observe all applicable laws and regulations. Unauthorized reproduction or transmission of this material is strictly prohibited. Dimensional accepts no responsibility for loss arising from the use of the information contained herein.
This material is not directed at any person in any jurisdiction where the availability of this material is prohibited or would subject Dimensional or its products or services to any registration, licensing, or other such legal requirements within the jurisdiction.
“Dimensional” refers to the Dimensional separate but affiliated entities generally, rather than to one particular entity. These entities are Dimensional Fund Advisors LP, Dimensional Fund Advisors Ltd., Dimensional Ireland Limited, DFA Australia Limited, Dimensional Fund Advisors Canada ULC, Dimensional Fund Advisors Pte. Ltd., Dimensional Japan Ltd., and Dimensional Hong Kong Limited.
RISKS: Investments involve risks. The investment return and principal value of an investment may fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original value. Past performance is not a guarantee of future results. There is no guarantee strategies will be successful.
UNITED STATES Dimensional Fund Advisors LP is an investment advisor registered with the Securities and Exchange Commission.
Investment products: • Not FDIC Insured • Not Bank Guaranteed • May Lose Value
Dimensional Fund Advisors does not have any bank affiliates.
Exhibit 1: MSCI data © MSCI 2025, all rights reserved. Indices are not available for direct investment. Their performance does not reflect the expenses associated with the management of an actual portfolio.
Exhibit 2: Data presented in the Growth of $1 chart is hypothetical and assumes reinvestment of income and no transaction costs or taxes. The chart is for illustrative purposes only and is not indicative of any investment. S&P data © 2025 S&P Dow Jones Indices LLC, a division of S&P Global. All rights reserved.
Indices are not available for direct investment. Their performance does not reflect the expenses associated with the management of an actual portfolio.
Investments provided through McMill Wealth Inc, a Nebraska Corporation, Registered Investment Advisor
This material is derived from sources believed to be reliable, but its accuracy and the opinions based thereon are not assured.
The articles and opinions in this publication are for general information only and are not intended to serve as specific financial, accounting or tax advice
Paper Tax Refund Checks Being Phased Out by the IRS
As part of a broader U.S. Department of the Treasury initiative to transition to fully electronic federal payments, the Internal Revenue Service (IRS) is phasing out paper tax refund checks for individual taxpayers for the 2026 federal tax filing season.1
Why is the IRS making this change?
The move towards electronic payments is designed to protect taxpayers from the possibility of a paper refund check being lost, stolen, altered, delayed, or returned to the IRS as undeliverable. Electronic refunds are also more cost efficient and faster than nonelectronic payments, which can take six weeks or longer to process.2
What does this mean for taxpayers?
No changes are being made to the process of filing a tax return. Taxpayers should continue to file their tax returns as they normally would, using one of the existing filing options. However, refund delivery will be shifting towards electronic payment methods. As a result, taxpayers should have all of their banking information (e.g., account and routing numbers) readily available when filing their returns.
While most tax refunds will be delivered by direct deposit or other secure electronic methods, there will still be alternative options available, such as prepaid debit cards or digital wallets, for those taxpayers who do not have access to a bank account.3
What if I owe the IRS money?
The IRS has stated that taxpayers should continue to use existing payment options until further notice but is strongly encouraging individuals and businesses to use electronic payment options, since they are easier, faster, and more secure. Further IRS guidance is expected soon.4
The IRS offers the following electronic payment options:
- IRS Direct Pay, which pays the IRS directly from your bank account without fees
- Electronic Federal Tax Payment System (EFTPS), a free system offered by the U.S. Department of the Treasury to pay your federal taxes
- IRS2Go, an IRS mobile app for easy and secure mobile payments
- Debit card, credit card, or digital wallet
For more information on the IRS transition towards electronic payments, visit irs.gov.
1-4) Internal Revenue Service, 2025
During the 2025 tax filing season, the IRS issued more than 93.5 million tax refunds to individual tax filers, and 93% of those, almost 87 million refunds, were issued through direct deposit.
Source: Internal Revenue Service, 2025
IMPORTANT DISCLOSURES
Broadridge Investor Communication Solutions, Inc. does not provide investment, tax, legal, or retirement advice or recommendations. The information presented here is not specific to any individual’s personal circumstances.
To the extent that this material concerns tax matters, it is not intended or written to be used, and cannot be used, by a taxpayer for the purpose of avoiding penalties that may be imposed by law. Each taxpayer should seek independent advice from a tax professional based on his or her individual circumstances.
These materials are provided for general information and educational purposes based upon publicly available information from sources believed to be reliable — we cannot assure the accuracy or completeness of these materials. The information in these materials may change at any time and without notice.
This communication is strictly intended for individuals residing in the state(s) of NE. No offers may be made or accepted from any resident outside the specific states referenced.
Prepared by Broadridge Advisor Solutions Copyright 2026.
State Approaches to OBBBA Income Tax Provisions
The One Big Beautiful Bill Act (OBBBA), enacted in July 2025, implemented several significant provisions, including new deductions for overtime and tips. States, in turn, have been evaluating how these federal tax changes will impact their own income tax revenue and administration. For individuals, how states respond to the federal legislation is significant because it may directly influence their state income tax obligations.
Since most states use the Internal Revenue Code (IRC) as the starting point for determining state taxation, each state must decide whether to adopt or reject (decouple) from these new federal income tax modifications. Nine states — Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming — do not impose a personal income tax and do not require conformity. For the states with an income tax, their legislative actions related to OBBBA generally fall into three categories: rolling conformity, selective (partial) conformity, and static conformity. 1
Rolling conformity states
Rolling conformity states automatically adopt amendments to the IRC, such as those in OBBBA, as the changes occur, unless the state decouples from a specific federal provision. Twenty states and the District of Columbia follow rolling conformity. 2
The primary advantage of rolling conformity is administrative clarity since the tax laws in these states will instantly reflect federal tax law changes without requiring separate state legislative action. This simplifies compliance for taxpayers, as federal income and deductions will apply for both federal and state purposes. However, states also retain flexibility to decouple if a federal provision will reduce state revenue or contradict state fiscal policy.
Unfortunately, rolling conformity may expose states to unanticipated revenue fluctuations. Acting quickly to decouple from federal provisions also can be politically difficult depending on the party makeup of the state legislators, and the transition period from state adoption to implementation may create compliance challenges or processing delays for both taxpayers and state agencies.
Selective conformity states
Selective, or partial, conformity states evaluate federal tax changes and adopt only the provisions that support revenue or policy goals while rejecting those that do not. There are four partial conformity states. 3
This hybrid type of conformity allows states to respond effectively to federal tax changes. For example, a state may elect to adopt the federal income tax deduction for tips to benefit lower-income taxpayers but decide to decouple from a different federal deduction that could reduce its tax revenue. Similarly, a state might choose to conform to a federal deduction related to overtime pay or other employment-based adjustments that align with its policy priorities while rejecting others that do not. Selective conformity allows states to protect their budgets.
However, partial conformity may create administrative challenges and unpredictability. Taxpayers will be required to apply separate federal and state income tax rules, while state agencies may have to use resources to evaluate and implement conformity. Additionally, taxpayers may face higher compliance costs and ambiguity in long-term tax planning.
Static conformity states
Static conformity states adopt the IRC on a specific date, which means that federal changes enacted after that date, such as OBBBA, do not apply unless the legislature later updates the conformity statute. Seventeen states follow this model. 4
This approach provides stability and legislative control over revenue. State lawmakers can assess the fiscal impact of each federal change before deciding to conform, meaning more budget predictability and less sudden revenue fluctuations. Taxpayers benefit from knowing that state tax law will not automatically shift in response to federal modifications.
However, problems with static conformity arise when federal law changes occur after a state’s conformity cutoff date, which means taxpayers must reconcile their state returns to older definitions or rules related to income, adding complexity. Gaps between conformity updates may result in certain taxpayers receiving federal tax benefits that do not carry through to their state returns.
For a complete list of how states conform to OBBBA provisions, visit https://taxfoundation.org/
Bottom line
State conformity to federal income tax changes, such as those introduced under OBBBA, can vary widely. Depending on where you live, some, all, or none of these federal changes may apply at the state level. Because state adoption of federal tax provisions is complex and continues to evolve, you should stay informed about how your state is responding to OBBBA provisions that affect you and consider consulting a qualified tax professional to better understand the potential differences between federal and state treatment.
1–4) Tax Foundation, July 31, 2025
IMPORTANT DISCLOSURES
Broadridge Investor Communication Solutions, Inc. does not provide investment, tax, legal, or retirement advice or recommendations. The information presented here is not specific to any individual’s personal circumstances.
To the extent that this material concerns tax matters, it is not intended or written to be used, and cannot be used, by a taxpayer for the purpose of avoiding penalties that may be imposed by law. Each taxpayer should seek independent advice from a tax professional based on his or her individual circumstances.
These materials are provided for general information and educational purposes based upon publicly available information from sources believed to be reliable — we cannot assure the accuracy or completeness of these materials. The information in these materials may change at any time and without notice.
This communication is strictly intended for individuals residing in the state(s) of NE. No offers may be made or accepted from any resident outside the specific states referenced.
Prepared by Broadridge Advisor Solutions Copyright 2025.
Wealth Management Winter Newsletter 2025
EDUCATING THE NEXT GENERATION ABOUT FAMILY WEALTH MANAGEMENT
Over the next few decades, an enormous amount of wealth is expected to pass from older to younger generations. This has been dubbed the “Great Wealth Transfer,” and one estimate suggests that $124 trillion will change hands by 2048. It’s an eye-popping figure, to be sure, but it also highlights the reality that many families are, or soon will be, navigating how to pass on their wealth. A top-of-mind question: Is the next generation ready to take on the responsibility?
Wealth is not just cash in the bank; it can include investments, real estate, businesses and more that require stewardship and foresight. Successful management means preserving and growing assets and using them wisely. Striking the right balance here is key: For the next generation to succeed, it takes intentional preparation and education.
PLANT THE SEEDS OF FINANCIAL LITERACY
Where to begin? In an ideal world, financial education starts in early childhood and is treated as an open and ongoing conversation as kids age. The goal is to build financial literacy gradually, so wealth management feels natural rather than overwhelming.
When kids are young, this might mean introducing simple topics like the difference between saving and spending. Managing an allowance can help put those ideas into practice. As kids get older you can begin introducing more complex topics, such as investing, compound interest, debt and taxes.
It’s equally important to engage adult children, many of whom may have received no other formal financial education. While 29 states now have K–12 financial education requirements in public schools, this focus has largely come to the forefront only in the last few years. If your kids are adults now, they may have missed out. So it’s worth finding out what they know, what they don’t know and what they’d like to know more about.
PUT STRUCTURE AROUND LEARNING
In addition to ongoing conversations about money, your family might benefit from more intentional ways of building financial literacy. Some families hold regular financial meetings where they share goals, key issues and address questions or concerns. Others put together more formal workshops with wealth advisors or other experts. There also is a wealth of credible educational content online that is built to both educate and engage audiences around financial literacy topics.
TURN CONVERSATIONS INTO ACTION
Eventually, theory should give way to practice. As younger family members learn the basics, you might consider providing a “practice portfolio,” giving them the chance to make investment decisions with small amounts of money and learn from their successes and mistakes. When family members have honed their knowledge, consider assigning them real responsibilities that match their skills and interest. This might mean relatively simple tasks like helping guide gifts made through a donor-advised fund. Or these responsibilities could be more involved, such as taking a role in the family business or helping to make investment decisions with the family’s wealth.
With your guidance and oversight, these experiences can help develop confidence and capability.
GROUND WEALTH IN PURPOSE AND VALUES
One of the most important things that helps guide families on how to grow and spend wealth is imparting a strong value system. Values can help you frame wealth as a tool rather than a goal.
Your values will be unique to you, but some worth considering may be:
• Stewardship: Recognizing the responsibility that comes with wealth. Stewardship encourages careful management and intentional choices so resources can benefit both current and future generations.
• Giving back: Using wealth to help create positive change in your community and the greater world.
• Self-worth beyond wealth: Remembering that wealth is a tool to achieve goals—whether gaining an education, pursuing passion or giving back, for instance—not a measure of personal value.
By grounding financial decisions in values, families can help prevent counterproductive or reckless financial decisions, foster responsibility and ensure wealth is not seen as something to be simply consumed.
KEEP THE CONVERSATION GOING
Discussing money isn’t always easy, and for many families, it’s downright taboo. While 66% of Americans say conversations about wealth are important, 62% say they never have them.3 But getting over this hurdle is incredibly valuable. The most successful families treat wealth education not as a one-time event, but as an ongoing process that evolves as your family grows and your financial picture changes. We can work with you to create an environment where family members can openly discuss the unique challenges and opportunities that come with wealth.
HAVE YOU RECEIVED A LETTER FROM THE SSA ABOUT “POTENTIAL PRIVATE RETIREMENT BENEFITS”?
TIMING AND PURPOSE OF LETTER
Each year—typically between August and October—the Social Security Administration (SSA) mails notices to individuals who may have unclaimed 401(k), pension, or other retirement benefits from a previous employer.
If you recently received one of these letters, don’t ignore it!
It could mean there’s a retirement account in your name waiting to be claimed.
HOW TO PROCEED WITH LETTER
Contact us and we would be happy to help you:
• Identify which employer and plan the notice refers to
• Locate and recover any old 401(k) or pension benefits
• Consolidate those assets into a Rollover IRA for easier management and continued growth
The letter usually comes from the Social Security Administration and includes a “Plan Number” and employer name. You will want to keep the letter handy when you reach out for guidance.
WILL THE MAGNIFICENT 7 STAY ON TOP?
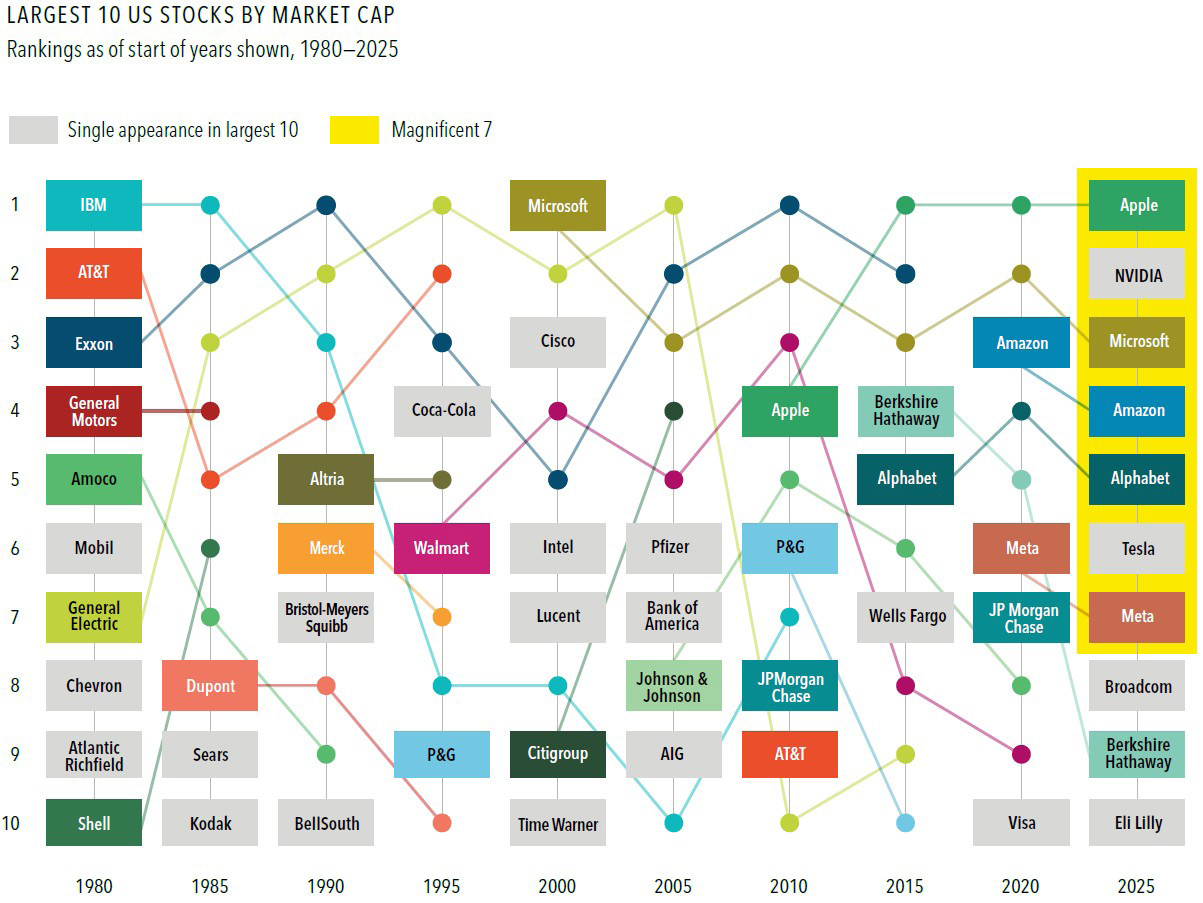
The Magnificent 7 entered 2025 among the Top 10 largest US stocks. But before making an outsize bet on gains from these technology giants, investors should consider a few lessons from market history.
It’s hard to stay on top. For example, only three of the ten biggest companies from 1980 made the 2000 list—and none of them was in 2025’s Top 10.
Industries ebb and flow. Technology-focused firms currently dominate the list. But in 1980, six of the ten largest companies were in the energy sector.
New technology doesn’t benefit only tech firms. Throughout history, companies across industries have used technology to innovate and grow.
Diversification enables investors to share in the success of today’s top companies while staying positioned to benefit from tomorrow’s market leaders.
Past performance is not a guarantee of future results.
Investing risks include loss of principal and fluctuating value. There is no guarantee an investment strategy will be successful.
The Magnificent 7 stocks are Alphabet, Amazon, Apple, Meta Platforms, Microsoft, NVIDIA, and Tesla.
This information is intended for educational purposes and should not be considered a recommendation to buy or sell a particular security. Named securities may be held in accounts managed by Dimensional.
Source: Dimensional, using data from the Center for Research in Security Prices and Compustat. Includes all US common stocks. Largest stocks identified at the end of the calendar year preceding the respective period
by sorting eligible US stocks on market capitalization using data provided by the CRSP, University of Chicago.
Dimensional Fund Advisors LP is an investment advisor registered with the Securities and Exchange Commission.
Investment products: • Not FDIC Insured • Not Bank Guaranteed • May Lose Value
Dimensional Fund Advisors does not have any bank affiliates.
PREDICTIONS
I recently read an article about predictions for our area for the upcoming winter.
In the article the author took a look at predictions made by the Farmers Almanac,
the Old Farmers Almanac, the Weather Service, the old wives-tales about ground
fog and the woolly worm whether it was fat or slim. Some of the various means
of predicting how the winter would go did coincide at least partially, but most of
them were quite different. In hindsight, when the winter is over is truly the only
way we will know for sure the outcome.
It is very similar with the markets. Everyone seems to have a different viewpoint
on how the markets will trend in the future. Even those with Nobel Prizes in
Economics will admit that they can not accurately predict the markets with any
consistency. The future is unknown until it turns into the present.
Not accounting for life-changing events, we have attempted to build a portfolio
that would fulfill your needs for the long-term based upon your risk aversion and
plans for your future. By focusing on your long-term plan, you shouldn’t need
to worry about what is going on daily in the market. You have a portfolio that is
diversified and based upon your wants and desires.
We are often asked “when would be a good time to invest?” No one actually
knows with any certainty the optimal time to invest. However, we usually say
that anytime is probably the right time to invest. The market will fluctuate
both higher and lower over time, and we can help you take advantage of those
fluctuations through rebalancing the investments within your investment
portfolio. Rebalancing provides the basis for selling “high” and buying “low”
during fluctuations in the market. We use this formula for a successful investment
experience over the long term.
So no matter what goes on in the market on a daily basis during 2026, don’t
worry about it. Your portfolio was designed specifically for you to be able to stick
with your financial plan. However, if you do experience a life-changing event,
please consult with us. We will be glad to help you determine if any adjustments
to your financial plan and investment portfolio need to be made under those
circumstances.
Remember to thank veterans and first-responders that you know for the many
sacrifices that they have made to make our country safe and free, and recognize all
of the blessings that we have enjoyed in 2025. We are very fortunate and thankful
to have had the opportunity to serve you as our clients in the past year and look
forward to continue our professional relationship with you in 2026.
Best wishes to you and yours to have a joyous holiday season, and a happy,
healthy, and prosperous new year!
Investments provided through McMill Wealth Inc, a Nebraska Corporation, Registered Investment Advisor
This material is derived from sources believed to be reliable, but its accuracy and the opinions based thereon are not assured.
The articles and opinions in this publication are for general information only and are not intended to serve as specific financial, accounting or tax advice